Yes, you can form a US LLC from Indonesia while living there (checked 18 September 2026). The U.S. side is built for foreign owners. The IRS tells applicants whose principal place of business is outside the United States to “apply by phone, fax or mail,” and adds that “You never have to pay a fee for an EIN” (IRS: Get an EIN, updated 19 August 2026). No SSN, no NPWP, no visit.
Whether you need one is the question worth your money, and for a lot of Indonesian freelancers the honest answer is no. PayPal runs an Indonesian business account and withdraws to Indonesian banks for free above IDR 1,500,000. Payoneer works.
Upwork pays into Indonesian banks in rupiah. Two local gateways publish card rates for Indonesian-registered businesses. And an Indonesian individual with turnover under IDR 4.8 billion can pay a 0.5% final tax, with the first IDR 500 million exempt, a rate no U.S. structure comes close to.
Against that: Mercury will not open an account for anyone living in Indonesia, Wise won’t let you hold a balance, Amazon accepts Indonesian sellers but won’t pay them into an Indonesian bank, and Stripe lists Indonesia as “Preview” rather than available.
Then there’s the part almost every English-language guide skips: Indonesia has controlled foreign company rules with a 50% threshold, an annual asset schedule in your SPT, and a Bank Indonesia reporting regime that names individuals in the regulation. This guide sets out what we verified, what we couldn’t, and where an Indonesian tax consultant has to take over.
In this guide: Can you form one? · What already works without one · Who actually benefits · Banking: check this first · The U.S. steps · Indonesia’s own rules · U.S. tax and the treaty · Getting the money home · What it costs · Who it suits and where to start
Can you form a US LLC from Indonesia?
On the U.S. side, yes. You can register the company, get its EIN and file its U.S. returns without living in the United States or setting foot there.
Three other questions decide whether it’s worth doing, and the state that registers your company answers none of them:
- Does the payment route you need actually require a U.S. company? From Indonesia, usually it doesn’t. The next section goes through what already works.
- Will a U.S. bank or payment account open for an owner who lives in Indonesia? Mercury won’t. Without an account, the LLC can’t receive anything, and you’ve bought a certificate.
- How does Indonesia treat it? You’re taxed on worldwide income, Indonesia has CFC rules, and there is an asset schedule in your annual return.
What already works from Indonesia without a U.S. company
Before paying for a company, check whether one of these already covers you.
PayPal Business
PayPal runs an Indonesian business sign-up with a local support line, promising you can “Terima pembayaran dari seluruh dunia”, receive payments from all over the world, in 130+ currencies across 200+ markets (PayPal Indonesia for business).
The fee table is the more useful proof. PayPal’s Indonesian merchant fee page, last updated 28 May 2026, puts Indonesia in the “all other markets” rows: 3.40% plus a fixed fee for domestic commercial transactions and 4.40% plus a fixed fee for commercial transactions received from outside Indonesia. Currency conversion carries a 3.0% markup over the base exchange rate for the Asia Pacific region (PayPal Indonesia merchant fees).
Getting the money out is the good news. Withdrawing to an Indonesian bank account is free above IDR 1,500,000 when no currency conversion is involved, and IDR 16,000 below that (PayPal Indonesia fees, updated 28 May 2026). That is a working, published, end-to-end route from a foreign client to your BCA or Mandiri account with no company on another continent.
If PayPal is the only reason you were looking at an LLC, stop reading and go open a PayPal business account.
Payoneer
Payoneer’s Indonesian site offers the two functions that matter: receiving from “2.000 pasar online, jaringan, dan platform”, 2,000 marketplaces, networks and platforms, naming eBay, Airbnb, Fiverr and Upwork, and withdrawing “dari akun Payoneer ke rekening bank Anda,” from your Payoneer account to your bank (Payoneer Indonesia, read 18 September 2026).
The page publishes no Indonesia-specific fees and says rates vary by region, so get them from Payoneer before you compare. We’re quoting none here.
Freelance marketplaces
Indonesia (IDR) is on Upwork’s list of countries supported for Direct to Local Bank withdrawals, at USD 0.99 per withdrawal (Upwork: Direct to Local Bank).
Fiverr pays out through PayPal (no fee), bank transfer via Payoneer (USD 1) or a Payoneer account (USD 3), and says “Each withdrawal method may have different location restrictions” without naming countries (Fiverr: withdrawing your earnings). Since PayPal and Payoneer both operate in Indonesia, an Indonesian Fiverr seller has a route, confirm it inside your own account rather than taking our word for it.
Local card gateways: Midtrans, DOKU and Xendit
Indonesia has a real domestic gateway market, which is more than most countries we write about can say. Two of the three publish their card rates:
- Midtrans (part of GoTo) lists 2.9% + IDR 2,000 per transaction for credit cards, covering Visa, Mastercard, JCB, American Express and UnionPay (Midtrans pricing, read 18 September 2026).
- DOKU lists 2.80% + IDR 2,000 for Visa, Mastercard and JCB, and 3.5% + IDR 2,000 for American Express (DOKU pricing, read 18 September 2026).
- Xendit‘s pricing page returned 403 to our checks, so we’re quoting no Xendit rate.
Two honest caveats before you treat this as solved.
First, neither Midtrans nor DOKU publishes a separate rate for foreign-issued cards on its pricing page, and neither page states whether international cards are accepted at the quoted rate or at all. That’s a question for their sales team, in writing, before you build a checkout on it. We are not claiming either way.
Second, you need a registered Indonesian business. Xendit’s own document list is the clearest published example: a PT, a CV or a Perseroan Perorangan all need a director’s KTP, an NPWP, a corporate NPWP and an NIB, and a Perseroan Perorangan additionally needs its Surat Pernyataan Pendirian and Sertifikat Pendaftaran Pendirian (Xendit: legal documents for Indonesian merchants).
A freelancer with a KTP and nothing else doesn’t qualify. Registering a Perseroan Perorangan in Indonesia is a far smaller job than forming and maintaining a company in Wyoming, but it is a job.
Amazon: accepted to sell, not paid out
Indonesia is on Amazon’s list of countries accepted for seller registration, sitting between India and Iraq (Amazon: accepted countries). So you don’t need a company to sell.
Getting paid is the gap. Neither Indonesia nor IDR appears on Amazon’s Seller Wallet list of countries you can transfer to your own bank account, and IDR is absent from the supported disbursement currency table, the list jumps from India (INR) to Japan (JPY) (Amazon: Seller Wallet, Amazon: supported bank accounts, both read 18 September 2026).
That puts Indonesia with Vietnam rather than the Philippines, where pesos are supported and the payout question never comes up. You need an account in a country Amazon does pay out to.
A U.S. LLC with a U.S. account is one answer; a receiving account from a provider like Payoneer is another, and cheaper, but we found no Amazon page naming Payoneer, so ask Amazon about your specific account before you build a business on the assumption.
Who actually benefits from a U.S. LLC
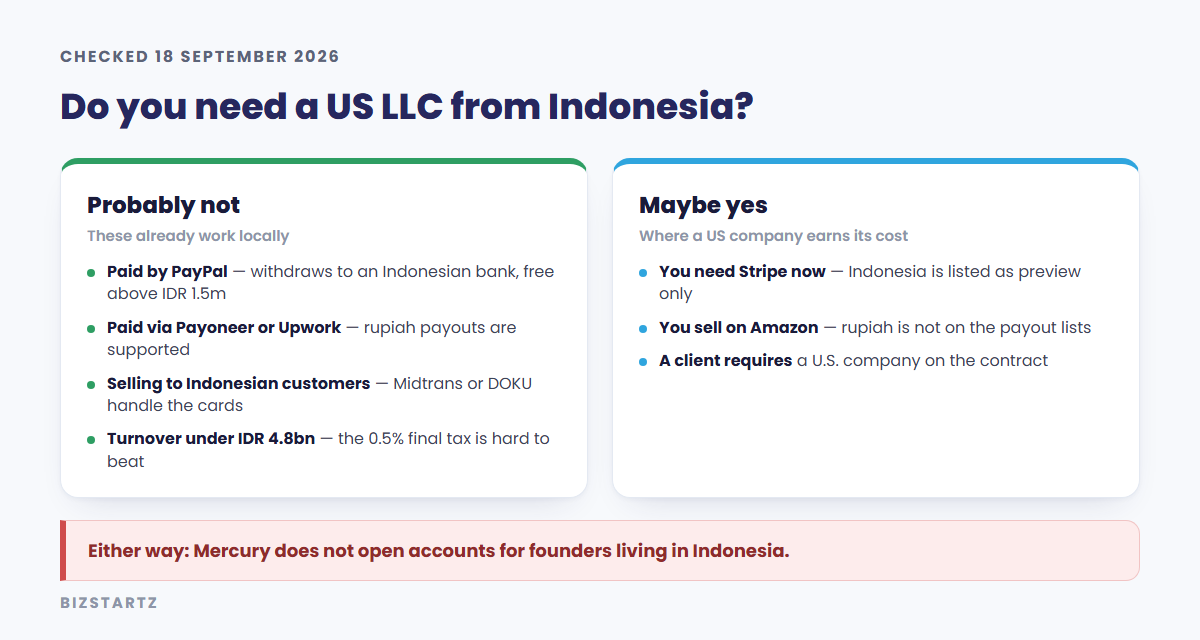
With PayPal, Payoneer, Upwork and two local gateways available, the case for an LLC narrows to three situations.
You need Stripe now
Indonesia is on Stripe’s global availability page, but in the “Preview” category, alongside India, with a “Contact sales” link rather than a sign-up. The supported list, where you can simply register, includes Malaysia, Singapore, Thailand and the UAE; it does not include Indonesia (stripe.com/global, checked 18 September 2026).
Read that precisely, because it’s the difference between Indonesia and its neighbours in this guide. Preview is not “unavailable”, it’s invite-only. If you have real volume and a clean business, talking to Stripe sales about an Indonesian account costs nothing and may be the shortest path.
If you need a live subscription checkout this quarter, or your billing tooling and app integrations assume a Stripe account you can open today, a U.S. company is the route people take. Our guide to opening a U.S. Stripe account as a non-resident covers the application.
Try Stripe’s Indonesian preview first. It’s a free email, and a local account sidesteps this entire guide.
You sell on Amazon and need somewhere to be paid
Covered above, and it’s Indonesia’s clearest LLC case. It’s a payout problem, not an eligibility problem. See running an Amazon seller account with a U.S. LLC, and read it alongside the fact that you can already register as an Indonesian seller.
A client or platform insists on a U.S. company
Some buyers will only contract with and pay a U.S. entity. If that’s a written requirement from someone actually paying you, not a hunch, it’s a legitimate reason. Ask them exactly what they need first, often it turns out to be a U.S. bank account to pay into rather than a U.S. company to contract with. And be aware a U.S. LLC doesn’t make you American on their paperwork; see the W-8BEN note below.
Who it probably doesn’t help
- Freelancers whose clients already pay through PayPal, Payoneer or a marketplace.
- Upwork freelancers. Indonesia is on the local-bank payout list.
- Anyone selling mainly to Indonesian customers.
- Anyone whose turnover is under IDR 4.8 billion and who qualifies for the 0.5% final tax, you would be swapping the cheapest small-business tax rate in the region for two countries’ filings.
- Anyone counting on Mercury.
- Anyone hoping a U.S. company puts their income outside Indonesia’s tax net. It doesn’t.
Banking from Indonesia: check this before you form
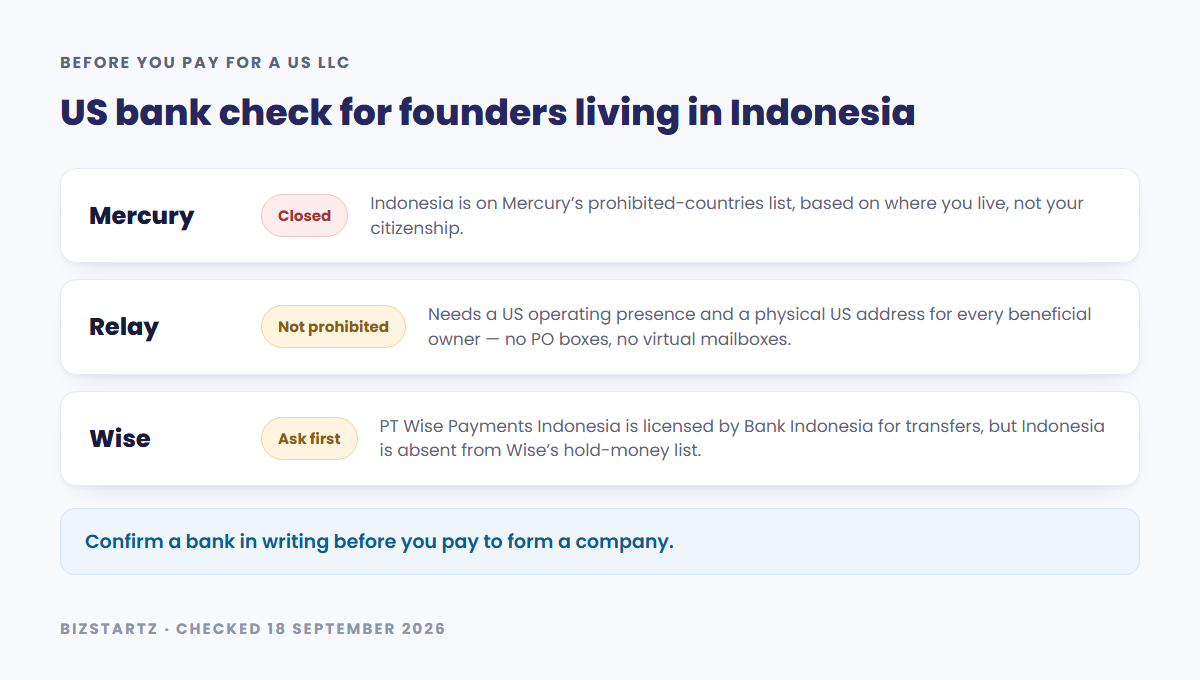
Mercury is closed to founders living in Indonesia
Mercury’s help centre says it is unable to open accounts for founders living in the countries and regions it lists, and that “this is based on your country of residence, not your citizenship or nationality.” Indonesia is on that list, as are Vietnam and the Philippines. Malaysia, Singapore and Thailand are not (Mercury: Prohibited countries, checked 18 September 2026).
Mercury does add that if you’re a citizen of a listed country but “currently reside elsewhere, your application may still be eligible, pending application review.” An Indonesian citizen genuinely living in Singapore is judged on Singapore.
A founder in Jakarta is not getting a Mercury account, whatever a formation package implies. Don’t solve this by entering an address you don’t live at, that’s a misrepresentation to a financial institution, and it’s the sort of thing that surfaces later, with your money inside.
Relay: not banned, but read the requirements
Indonesia is not on Relay’s prohibited-countries list, which Relay applies to any business owner who “holds citizenship or residency” in a listed country (Relay: Prohibited countries, updated 11 August 2026).
Not being banned isn’t the same as qualifying. Relay’s documents page says it accepts U.S.-registered businesses owned by non-U.S. citizens or residents “provided the business has an operating presence in the U.S.,” and asks each beneficial owner for a passport, an “SSN or passport number,” and a “physical U.S. address (no PO boxes, no virtual mailboxes)” (Relay: Required documents, updated 11 August 2026).
The page doesn’t explain how an owner living in Bandung meets the U.S. address line, and we won’t guess on Relay’s behalf. Ask them in writing, before you form the company.
Wise
Indonesia is not on Wise’s list of countries where you can hold money; the “I” entries run Iceland, Ireland, Israel, Isle of Man, Italy (Wise: where do I need to live to hold money, checked 18 September 2026). So the personal Wise balance and USD account details that Filipino founders lean on aren’t available to you.
That’s narrower than it sounds, and worth understanding. Wise does operate in Indonesia: “PT Wise Payments Indonesia is licensed by Bank Indonesia (BI) as a Fund Transfer Operator” (Wise: regulatory permissions).
A transfer operator moves money to you. It isn’t the same as a balance you can hold and get account details for. Treat Wise as a way money reaches your Indonesian bank, not as the LLC’s account, and confirm with Wise before relying on it either way. Whether Wise Business accepts a U.S. LLC whose owner lives in Indonesia is decided at verification, and we found no Wise page that answers it.
What to check before you pay for a company
- Which bank or payment account will the LLC use, and does its published policy accept an owner living in Indonesia?
- Does it need a U.S. address for you personally, and would a registered-agent or mail-forwarding address count? Get the answer in writing, from them.
- Does Stripe, or Amazon, or whichever platform you formed the company for, accept that account for payouts?
- What’s your second option if the first application is declined?
Our U.S. payment and banking access by country table compares these providers side by side. It carries rows for India, Pakistan, Nigeria, the UAE and the Philippines, not yet Indonesia, the checks above are the Indonesia row.
The U.S. steps, briefly
We’ve written each step up in detail, so here’s the order and the Indonesia-specific notes.
- Confirm a bank first. Read the section above before anything else. It’s the step most likely to fail, and checking costs nothing.
- Choose a state. Wyoming is our usual example: Articles of Organization cost USD 100, and the annual report license tax is USD 60 or two-tenths of one mill on the company’s Wyoming assets, whichever is greater (Wyoming Secretary of State fee schedule, effective 1 July 2026). Delaware is the other name people arrive with, and its LLC annual tax is fixed at USD 400 by statute, due on 1 June (6 Del. C. § 18-1107). Compare properly in which U.S. state to choose as a non-resident.
- Appoint a registered agent in that state. Wyoming charges USD 350 to reinstate an LLC that lost its registered agent, so keep it renewed.
- Get the EIN without an SSN, by phone, fax or mail — not the online tool, which needs a U.S. taxpayer number. See how to get an EIN without an SSN.
- Open the U.S. account, then apply to Stripe or Amazon or whichever platform you formed the company for.
One thing you no longer have to do: beneficial ownership reporting. FinCEN’s final rule, issued 11 August 2026 and effective 14 August 2026, means U.S. companies “are exempt” and “are no longer required to file BOI reports” (FinCEN: Beneficial Ownership Information). Any package still charging you for a BOI filing on a U.S.-formed LLC is selling you nothing.
Indonesia’s own rules: the part the other guides skip
We are not Indonesian tax advisers, and nothing here says this route is legal or illegal for you. What follows is what we could verify from DJP, Ministry of Finance and Bank Indonesia sources, what we couldn’t, and the questions to take to a konsultan pajak.
You’re taxed on worldwide income
DJP’s guidance on determining resident status, drawing on PER-23/PJ/2025, makes an individual a resident taxpayer by residing in Indonesia, by being present more than “183 (seratus delapan puluh tiga) hari dalam jangka waktu 12 (dua belas) bulan,” or by being present in a tax year with the intent to reside.
A resident individual’s income is taxable “baik yang berasal dari Indonesia maupun dari luar Indonesia”, whether it comes from Indonesia or from outside it (DJP: Penentuan Subjek Pajak Dalam Negeri dan Subjek Pajak Luar Negeri, 9 December 2025).
Money reaching you from a Wyoming LLC is income from outside Indonesia. That rule covers it. Forming a company abroad does not move your income out of Indonesia’s net, and anyone selling you an LLC on that basis is selling you a problem.
The progressive rates under UU HPP, as DJP sets them out, are five bands: 5% on taxable income up to IDR 60 million, 15% above IDR 60 million to IDR 250 million, 25% above IDR 250 million to IDR 500 million, 30% above IDR 500 million to IDR 5 billion, and 35% above IDR 5 billion (DJP: Lapisan Pajak Penghasilan Kian Progresif, 22 October 2021). Confirm the current-year figures with a consultant; these are the bands DJP published when the law took effect.
The 0.5% rule that usually beats an LLC
This is the number that should decide most of these conversations, and it barely appears in English-language LLC guides.
An Indonesian individual taxpayer with gross turnover not exceeding IDR 4.8 billion in a tax year can use the 0.5% final income tax, and the first IDR 500 million of turnover in a year is not taxed at all.
Under PP 20/2026, effective 22 April 2026, individuals and Perseroan Perorangan can now use that rate indefinitely as long as they still meet the criteria, DJP’s phrasing is that they can use it “tanpa khawatir masa berlakunya berakhir,” without worrying about it expiring, where earlier rules imposed a fixed number of years (DJP: PP 20/2026 — Tarif PPh 0,5% bagi UMKM Orang Pribadi Berlaku Selamanya, 3 June 2026).
Work the arithmetic before you form anything. A freelancer billing IDR 800 million a year pays 0.5% on the IDR 300 million above the exemption, IDR 1.5 million in tax, on a Jakarta laptop, with no U.S. filings.
The LLC alternative is USD 100 to file in Wyoming and at least USD 60 every year after that, before a registered agent, before a Form 5472 preparer, before bank charges, and it does not remove the Indonesian tax anyway. Whether your specific income qualifies as usaha turnover for the final rate is a question for your consultant, but ask it before you shop for a state.
Controlled foreign company rules: PMK 93/PMK.03/2019
Indonesia has CFC rules, and they’re the reason “just leave the profit in the LLC” is not the plan people think it is.
Under PMK 93/PMK.03/2019, which amends PMK 107/PMK.03/2017, a non-listed foreign business entity is directly controlled where a resident taxpayer “owns direct equity participation at least 50% (fifty percent) of the amount of paid in capital,” or holds at least 50% “together with other resident Taxpayer” (PMK 93/PMK.03/2019, official English text on pajak.go.id). A single-member LLC is 100% owned. You are over that line on day one.
Where the rules got narrower, and this matters: since the 2019 amendment the deemed dividend is calculated on the net amount after tax of specified, largely passive income, dividends, interest, rent, royalties, and gains from the sale or transfer of assets.
DJP describes the shift as moving from taxing all post-tax profit to a transactional approach aimed at passive income with BEPS risk (DJP: CFC Rules — Revisi Regulasi, Cegah Distorsi). Fees for consulting work, software or products sold through the LLC are not in that list.
What we could not settle, and it’s the crux. Three things:
- Whether a single-member U.S. LLC, a disregarded entity for U.S. tax, with no separate U.S. return of its own, is a “badan usaha luar negeri” for these rules at all, or whether DJP would simply look through it and treat its income as yours as it arises. We found no DJP guidance either way.
- Whether the rules bite on an individual. The regulation is addressed to resident Taxpayers, a category that in Indonesian law includes individuals, but we found no published DJP example applying it to an individual with a small foreign company.
- The exact timing rule. The worked example in the regulation puts the deemed dividend at the end of the seventh month after the foreign entity’s tax year ends, to be reported in the resident’s annual return for that year. Confirm the rule that applies to your facts rather than that example.
These are answerable questions. They are answerable by an Indonesian tax consultant with the regulation open, in an hour, for less than the cost of one year of an LLC you may not need.
Reporting: the SPT asset schedule, and Bank Indonesia
Your SPT. DJP is direct that “Setiap Wajib Pajak wajib mengisi Surat Pemberitahuan dengan benar, lengkap, dan jelas”, every taxpayer must complete the return correctly, completely and clearly, and the individual return includes a list of assets held at year end.
DJP’s own framing is reassuring on one point: listing an asset does not itself create tax, as long as its origin is clear and the income behind it was reported (DJP: Mudahnya Lapor Harta di SPT). Your interest in a U.S. LLC and the balance in its bank account are assets. How to classify and value them in the harta schedule is a question for your consultant, not for us.
Bank Indonesia. This one deserves a careful answer, because the regulation and its implementing rules don’t say quite the same thing.
PBI No. 21/2/PBI/2019 defines a Pelapor as “Penduduk yang melakukan kegiatan LLD”, a resident carrying on foreign exchange activity, and its list of reporters expressly includes “perseorangan,” individuals.
Foreign Financial Assets (AFLN) are defined as a resident’s claims on non-residents, in foreign currency or rupiah, “dalam bentuk kas valuta asing, simpanan, surat berharga, dan aset luar negeri lainnya” (PBI 21/2/PBI/2019). A U.S. bank balance is a deposit with a non-resident.
But the implementing regulation is narrower. PADG No. 21/7/PADG/2019 sets out who actually files, and the Pelapor categories it lists are non-bank financial institutions, non-financial business entities and other bodies, not individuals (PADG 21/7/PADG/2019).
So the honest reading is that a private individual is unlikely to have a monthly LLD filing obligation, while Bank Indonesia retains the power to require information about foreign exchange activity from residents.
We can’t take it further than that, for two reasons: we read these two instruments, not the whole framework, and Bank Indonesia issued PBI No. 9 of 2024 on Pengelolaan Lalu Lintas Devisa in December 2024, which we did not read in full. Do not treat this paragraph as clearance. If you’re going to hold meaningful money in a U.S. account, ask a consultant, or Bank Indonesia’s own contact centre, whether anything is due from you.
Questions to take to an Indonesian tax consultant
- Is a single-member U.S. LLC a foreign business entity for PMK 93/PMK.03/2019 purposes, or would DJP look through it to me?
- If the CFC rules do apply, does the deemed dividend reach my income at all, given that it’s limited to dividends, interest, rent, royalties and asset gains?
- When the LLC pays me, is that business income, foreign employment income, or a dividend, and which rate applies?
- Can I use the 0.5% final rate on this income, or does routing it through a foreign company take me out of it?
- How do I claim credit in Indonesia for any U.S. tax paid, and what do I need to hold to support it?
- How should the LLC interest and its bank balance appear in my SPT harta schedule?
- Do I have any Bank Indonesia reporting duty as an individual holding financial assets abroad?
U.S. tax: Form 5472 every year, and what the treaty does
A single-member LLC owned by a non-U.S. person is a “foreign-owned U.S. disregarded entity.” Every year it files a pro forma Form 1120 with Form 5472 attached, even when it owes no U.S. tax and even when it earned nothing. It can’t e-file: the IRS instructions say “If you are a foreign-owned U.S. DE, you cannot file Form 5472 electronically,” and direct it by fax to 855-887-7737 or by mail to Ogden, Utah.
The penalty for failing to file is USD 25,000, with a further USD 25,000 if the failure continues more than 90 days after an IRS notice (IRS Instructions for Form 5472, Rev. 12/2024). More in our guide to Form 5472 for foreign-owned LLCs.
You file a personal U.S. return, Form 1040-NR, only when you have U.S. income that requires it. The IRS taxes a non-resident alien’s income effectively connected with a U.S. trade or business “at graduated rates” after allowable deductions, and FDAP income “at a flat 30 percent (or lower treaty rate, if qualify)” with no deductions (IRS: Taxation of nonresident aliens, updated 17 February 2026).
Whether serving foreign clients through a U.S. LLC from a desk in Surabaya creates effectively connected income is a real question with a real answer for your facts. Get it from a U.S. tax preparer, not from a formation company.
When a U.S. client or platform asks for a tax form, it’s yours to give, not the company’s. The IRS instructions say “the owner of a disregarded entity (including an individual), rather than the disregarded entity itself, must submit the appropriate Form W-8BEN” (IRS Instructions for Form W-8BEN, Rev. 10/2021). That’s you, in Indonesia, signing as a non-U.S. person.
The treaty, and what it doesn’t do
Indonesia is on the IRS list of countries with a U.S. income tax treaty in force (IRS: treaties A to Z, updated 3 January 2026, checked 18 September 2026). That is a genuine advantage over Vietnam, which isn’t.
The treaty was signed at Jakarta on 11 July 1988; Article 8 exempts a resident’s business profits from tax in the other state unless they’re carried on through a permanent establishment there, and Article 23 provides the credit mechanism, each state allowing a credit for the other’s tax within its own domestic limits (treaty text on irs.gov).
Three things the treaty does not do:
- It doesn’t remove the Form 5472 filing. That’s an information return, not a tax.
- It doesn’t stop Indonesia taxing you. Article 23 gives relief from double taxation, not from Indonesian taxation.
- It doesn’t apply automatically. Claiming treaty benefits on a Form W-8BEN generally requires a taxpayer number: a U.S. TIN (an SSN or ITIN) on line 5, or a foreign TIN — your NPWP — on line 6a, per the same IRS instructions. Fill the form in without one and the withholding agent may apply the statutory rate regardless.
Getting the money home
From the LLC’s U.S. account, the realistic routes to Indonesia are an international wire to your Indonesian bank, a Wise transfer to your Indonesian bank account, or a Payoneer withdrawal. There’s no Wise balance to park it in first, Indonesia isn’t on the hold-money list. We haven’t verified wire fees, which vary by bank.
Expect your Indonesian bank to ask what the money is for, and have invoices, a contract or the LLC’s records ready. That’s ordinary anti-money-laundering practice, not an Indonesian quirk.
What the money is matters as much as how it travels. A payment from your LLC for work you did looks like business income. A distribution of the LLC’s profit is a return on a company you own abroad, which is the doorway to the CFC section above and to a different line on your SPT. Settle which one fits your setup with a consultant before the first transfer, not after the fifth.
What it costs
Only figures we could source:
- Wyoming filing: USD 100 to file Articles of Organization, then an annual report license tax of at least USD 60 a year (Wyoming fee schedule, effective 1 July 2026). Third-party guides widely quote USD 102.40 for filing online, on the basis that WyoBiz adds a card processing fee; that surcharge does not appear on the Secretary of State’s own fee schedule, so treat the extra USD 2.40 as reported rather than verified.
- Delaware, if you go that way: USD 400 a year in LLC annual tax, due 1 June, by statute (6 Del. C. § 18-1107).
- EIN: free from the IRS.
- BOI reporting: nothing. U.S.-formed companies have been exempt since 14 August 2026.
- Formation service: Bizstartz packages are USD 199, USD 299 or USD 699, plus the state fee (our pricing page). Other providers charge differently.
- Every year: the state’s annual tax, registered agent renewal, and the Form 5472 filing, whether you prepare it or pay someone.
- Not priced here: registered agent renewal, bank and wire fees, Stripe’s pricing, Payoneer’s fees, and an Indonesian tax consultant. Get quotes for all of them. The consultant is the line most people leave out, and on the CFC question it’s the one doing the most work.
Set that total against the alternative: PayPal at 4.40% plus a fixed fee to receive from abroad, a 3.0% conversion markup and a free withdrawal above IDR 1,500,000, with no company, no registered agent and no U.S. filing, and, if you qualify, a 0.5% final tax with the first IDR 500 million exempt. At low volume that comparison isn’t close.
Who this suits, and where to start
It can make sense if you need Stripe and Stripe’s Indonesian preview hasn’t opened for you; or you sell on Amazon and Indonesia’s absence from the payout lists is blocking you; or a client genuinely requires a U.S. company.
Your revenue should cover the yearly filings and fees, you should have a bank that accepts an owner living in Indonesia confirmed in writing, and an Indonesian tax consultant should have looked at the CFC question and at what it does to your 0.5% position.
It probably doesn’t if PayPal, Payoneer or Upwork already covers how you get paid, your customers are in Indonesia, or your turnover sits comfortably under IDR 4.8 billion. And it never makes sense as a way to stop Indonesia taxing income it already taxes.
Start with the cheap checks. Email Stripe about the Indonesian preview. Work out which platform you actually need. Confirm a bank in writing. Ask a consultant the seven questions above. Form the company last, it’s the easy part, and the part that’s hardest to undo cleanly.
If you decide a U.S. company fits, Bizstartz forms U.S. LLCs for non-resident founders and handles the state filing, operating agreement, first-year registered agent and EIN application (U.S. company formation). A free 30-minute consultation is a sensible place to test the U.S. side, including which bank is realistic for you, before you spend anything. We can’t advise on Indonesian tax, and you shouldn’t take that from a formation company anyway.
This guide was researched with the help of AI tools. Every legal, fee and availability claim links to the source it came from, and the sources were checked on 18 September 2026. Where we couldn’t confirm something, and on Indonesia’s CFC treatment of a single-member LLC there is a lot we couldn’t, the text says so. Rules in this area change often, so check the linked sources again before you act.
🎯 Ready to start? Claim your free consultation and we'll map out your US LLC formation strategy — EIN, banking, and the right state for your country.

Ready to start your company?
Bizstartz handles formation, EIN, banking and compliance for founders worldwide.