The Relay prohibited countries list runs to 31 names, and Nepal, Bangladesh, India, Indonesia, Vietnam, the Philippines and Sri Lanka are not among them. That is not the same as Relay opening an account for you. Relay’s own help pages disagree on whether every owner needs an SSN and a US address (see the US address question below), so if you live outside the US, treat Relay as uncertain until its team confirms your setup in writing.
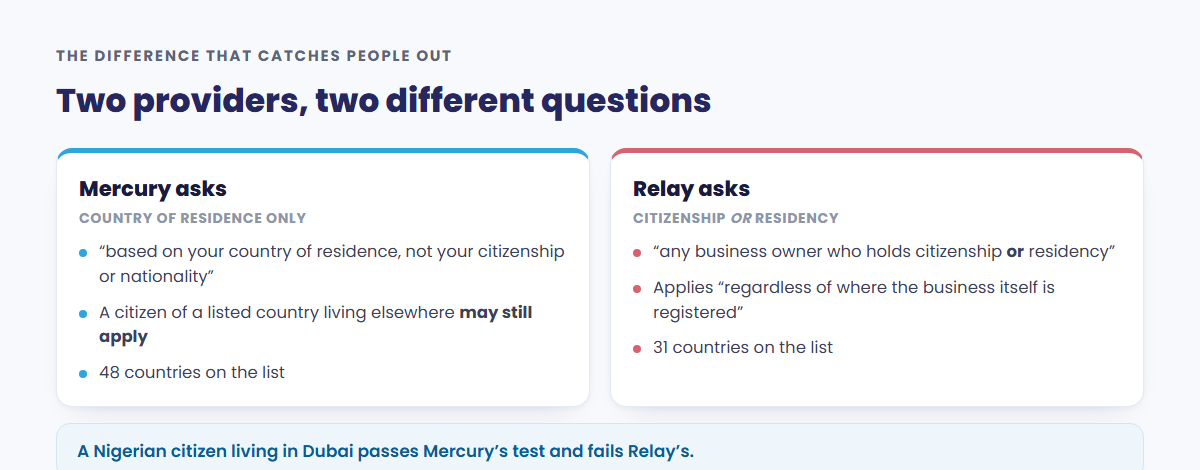
There is a catch, and it is not the one people expect. Mercury asks where you live. Relay asks where you live or what passport you hold, and either answer on its own is enough to stop the application. So the standard escape route from a Mercury refusal, being a citizen of a restricted country while residing somewhere else, works on Mercury and fails on Relay.
This page covers who Relay lets in, the exact list, and the three other country lists Relay publishes that decide whether the account is actually useful once you have it. It is the companion to our breakdown of Mercury’s prohibited countries, which covers the same ground for the provider most non-resident founders try first.
Every Relay figure on this page was read from Relay’s own help centre on 4 November 2026. Relay’s prohibited-countries page carried “Updated August 11, 2026” on that date.
The rule, in one sentence
Relay’s help centre states it plainly:
“Relay cannot open accounts for business owners holding citizenship or residency in certain countries due to Thread Bank policy, U.S. sanctions, and federal law.”
Three phrases in there do the work.
“Or.” Citizenship or residency. Not both. A passport from a listed country is enough on its own, and so is a residence permit, and neither cancels the other out.
“Business owners.” Not just the applicant. Relay’s wording:
“The restriction applies to any business owner named on the Relay Account application, including beneficial owners. If a required owner holds citizenship or residency in a listed country, Relay cannot open the account, regardless of where the business itself is registered.”
One co-founder on the list closes the account for everyone. And “regardless of where the business itself is registered” disposes of the most common piece of bad advice in this space: no, a Wyoming LLC does not neutralise a country rule. The entity is American. The owners are still who they are.
“Thread Bank.” Relay is not the one deciding. More on that below, because it explains why the list moves.
The good news, from the same page:
“In most cases, yes. Relay permits U.S. entities with non-U.S. citizen owners, and Relay also permits businesses based internationally.”
The 31 Relay prohibited countries, as Relay publishes them
Reproduced exactly, including Relay’s own spellings:
- Afghanistan
- Belarus
- Bosnia and Herzegovina
- Burkina Faso
- Burma (Myanmar)
- Burundi
- Cambodia
- Central African Republic
- Congo (Democratic Republic)
- Cuba
- Ethiopia
- Guinea-Bissau
- Haiti
- Iran
- Iraq
- Lebanon
- Libya
- Mali
- Nicaragua
- Nigeria
- North Korea
- Pakistan
- Russia
- Somalia
- South Sudan
- Sudan
- Syria
- Ukraine
- Venezuela
- Yemen
- Zimbabwe
Relay adds the warning that matters most:
“This list reflects current Thread Bank policy and applicable U.S. sanctions, and it can change without notice.”
Check it yourself before you apply. A list that can change without notice will eventually change without notice, and an article is a snapshot.
Where Relay is stricter than Mercury, and why it surprises people
Mercury’s restriction is about residence. Relay’s is about residence or citizenship. That single difference reverses the usual advice.
Take a founder with a Nigerian passport living in Dubai. Nigeria appears on both lists, so both providers have an opinion about him.
- Mercury looks at where he lives. He lives in the UAE, which Mercury does not restrict. He has a realistic shot.
- Relay looks at citizenship or residency. His passport is Nigerian. That ends it, no matter that he has lived in Dubai for a decade and holds an Emirates ID.
Relocation is the standard answer to a banking refusal, and it is a genuine answer for Mercury. It does nothing for Relay. Nothing you can do to an address changes what a passport says.
The reverse case is more cheerful. A founder who is a citizen of a country neither provider lists, but who lives in a Mercury-restricted country, fails Mercury’s residence test and passes Relay’s. For that person Relay is not the fallback — it is the better first application.
One thing to be unambiguous about: you cannot answer these questions creatively. Misstating citizenship, residency or ownership on a bank application is fraud, and the way it surfaces is a frozen account with your money inside it. There is no version of that trade that is worth it.
Who this is genuinely good news for
We compared Relay’s 31 names against the 48 prohibited countries plus 4 sanctioned entries published on Mercury’s restricted list. The overlap is heavy but not total.
29 of Relay’s 31 also appear on Mercury’s list. If Relay says no, Mercury almost certainly says no too. Our US Fintech Lockout Index combines these lists with other providers’ published rules into one score for each country.
Two are on Relay’s list and not Mercury’s: Ethiopia and Guinea-Bissau. Ethiopian founders in particular should note this, because the usual assumption that Relay is the softer option is backwards for them.
Twenty-two countries are on Mercury’s list and not Relay’s. These are the founders nobody has told:
Albania, Angola, Bangladesh, Bhutan, Cameroon, Congo (the), Croatia, Eritrea, Gambia, Indonesia, Kyrgyzstan, Latvia, Lesotho, Liberia, Maldives, Mozambique, Nepal, Palestine (State of), Philippines, Uzbekistan, Vanuatu, Vietnam.
(Mercury also lists Russian-occupied regions of Ukraine separately. Relay’s blanket listing of Ukraine covers that ground already.)
Nepal, Bangladesh, Indonesia, Vietnam and the Philippines are the five that matter most to the founders we work with, and Relay does not restrict account opening for any of them. India and Sri Lanka appear on neither list.
Before you celebrate, read the next section. Getting the account open and being able to use it are two different questions, and Relay answers them with two different lists.
Relay publishes four country lists, not one
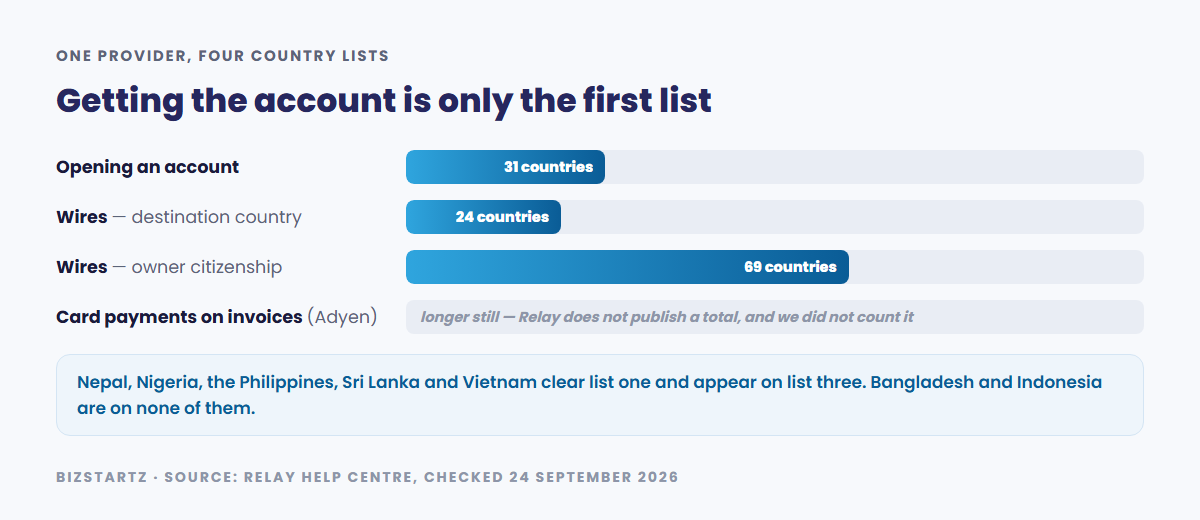
This is the part that costs people weeks, and we have not seen it written down anywhere. The prohibited-countries list decides whether you get an account. Three other lists decide what the account can do. They are separate documents with separate rules and largely different contents, and a country absent from one can sit squarely on another.
All four were read on 4 November 2026, and all four carried “Updated August 11, 2026”.
1. Prohibited countries — can you open an account at all
The 31 names above. Citizenship or residency, every beneficial owner.
2. International wires — a second, much longer citizenship list
Relay’s wire restrictions article carries two lists of its own. The first names countries Relay will not move money to or from at all: “Relay cannot process international wires, sending or receiving, involving any of the following countries.” That is roughly the sanctions set you would expect.
The second is the one to pay attention to. Its scope, in Relay’s words: “Relay cannot offer international wire services on a Relay Account when a beneficial owner holds citizenship in any of the following countries or territories.”
Read that carefully. It is not “you cannot wire to Nepal.” It is that international wire functionality is switched off on the whole account because of who owns it. We counted 70 entries on that list on 4 November 2026 — Relay does not publish a total, so treat the number as our count rather than Relay’s.
Among them: Nepal, the Philippines, Vietnam, Sri Lanka and Nigeria, alongside Ethiopia, Guinea-Bissau, Kenya, South Africa, Jamaica, Panama, Moldova, Bulgaria and a long tail of others.
So a Nepali founder can open a Relay account, and — going by Relay’s published rule — cannot use it to send or receive international wires. For a founder whose whole reason for wanting a US account is moving money across a border, that is close to the entire use case.
India, Bangladesh, Pakistan and Indonesia did not appear on that list when we read it.
3. Card payments on Invoices and Quick Requests — an Adyen list
If you want customers to pay an invoice by card, a third list applies. Relay’s wording: “Relay cannot process card payments through Invoices or Quick Requests when any business owner has citizenship or residence in one of the countries listed below.” Relay names the source: “Card payment acceptance in Relay Invoices and Quick Requests is powered by Adyen, and this list reflects Adyen’s global risk policies.”
Relay says so itself: “The policy is separate from Relay’s account-opening rules and separate from the list of countries where Relay cards themselves are not accepted at merchants.”
This list is far longer than the other three. Nepal, Bangladesh, Pakistan, Vietnam, Indonesia, the Philippines, Sri Lanka and Nigeria are all on it. India was not. We are deliberately not quoting a total, because the list is long enough that any count we gave you would be a number we produced rather than one Relay published — go and look at it.
Being on it is not fatal. Relay: “Yes, you can still accept payments through Relay using non-card payment methods. Card acceptance is the only channel affected by this list, and the following options remain available on Invoices and Quick Requests: ACH transfers (U.S. bank accounts only), Wire transfers, Online Bank Transfer (Plaid).” Note the parenthesis on ACH — US bank accounts only.
4. Countries where Relay cards are declined at merchants
The fourth list is about spending, not receiving. Relay: “Your Relay Visa® Debit Card and Relay Visa® Credit Card are automatically declined at merchants processing in the countries and territories listed below due to Visa’s international transaction policies.”
The trap here is that it keys off where the merchant processes, not where you are. Hong Kong, Turkey, Cyprus, Malta, Morocco, Lithuania, Macao and Jordan are on it — places where plenty of ordinary suppliers and SaaS vendors process payments. Pakistan, Nigeria, the Philippines, Vietnam and Sri Lanka appear as well.
What that means in practice
For a founder in, say, Nepal or the Philippines, the honest summary is: Relay does not prohibit your country, but its pages disagree on whether you need an SSN and a US address (see the next section). If Relay does open an account for you, it will work as a US domestic account. ACH in and out, a debit card, sub-accounts, bookkeeping integrations — all fine. International wires and card-on-invoice acceptance, going by Relay’s published lists, are not.
That is still worth having, and for some businesses it is exactly enough. But it is a different product from the one you thought you were applying for, and it is worth knowing before you spend two weeks on documents. Our country-by-country guide to US banking and payment access maps which platform actually works from where.
The US address question
Relay’s help pages do not agree on this, so here is what each one says (all read on 4 November 2026).
The required-documents article asks every beneficial owner for a “Physical U.S. address (no PO boxes, no virtual mailboxes)” and an SSN or passport number, and says Relay accepts businesses owned by non-US citizens or residents “provided the business has an operating presence in the U.S.”
The account-opening guide asks for each owner’s residential address without saying it must be in the US, but says every beneficial owner must have a valid SSN.
The two address articles go the other way. They say non-US residents can use a registered agent address as the business’s legal address, as long as every owner gives a real residential address, and they accept a home address “domestic or international” as the operating address. A registered agent address can never be the operating address or anyone’s personal address, and PO boxes, virtual mailboxes and mailbox rental services are refused everywhere.
Where official pages differ this much, plan on the strictest reading.
What to do with that: if no owner has a physical US address, treat Relay as unavailable and look at the alternatives in our guide to opening a US bank account as a non-US resident. If you want to try anyway, ask Relay’s Customer Experience team before you apply and describe your actual setup. Their written answer is what counts.
One adjacent point that is unambiguous: Relay’s sole-proprietorship route is closed to most non-residents. Relay states outright that it “cannot support sole proprietors without a valid SSN or a physical U.S. address.” If you are outside the US, that is an argument for forming an LLC rather than trying to bank a sole proprietorship.
What else has to be true
Country eligibility is the gate people fail at, but it is not the only one.
- A real US entity. Relay’s LLC checklist asks for Articles of Organization or a Certificate of Formation, and a signed Operating Agreement if the LLC has more than one member.
- An EIN. Non-negotiable, and it is the step that most often stalls a non-resident timeline. You can get one without a Social Security Number — our explainer on what an EIN is and how non-residents obtain one covers the SS-4 route.
- Every 25% owner named. Relay defines a beneficial owner as “anyone who owns 25% or more of the business, directly or indirectly, or who holds significant management responsibility,” and they all have to be invited during signup. Have their emails ready — and remember that each of them is independently subject to the country rule.
- Identity documents that verify. Relay’s required-documents article asks each beneficial owner for an SSN or passport number, and non-US citizens must show a passport. Its account-opening guide says every beneficial owner must have a valid SSN. If you have no SSN, ask Relay before applying rather than after.
- An industry Relay’s partner bank will bank. Relay maintains a separate prohibited-industries list. Worth two minutes before you start.
Is Relay a bank?
No, and Relay says so. Its own disclosure: “Relay is a financial technology company and is not an FDIC-insured bank.” Banking services are “provided by Thread Bank, Member FDIC.” Relay also names Community Federal Savings Bank in connection with international payment services.
That structure is why the prohibited list exists at all. The rule is Thread Bank’s, which is why Relay’s page attributes it to “Thread Bank policy” and warns that it “can change without notice.” Relay is passing on a decision made a layer beneath it. It also means a change in banking partner could move the list in either direction without any change in how Relay itself feels about you.
On deposit insurance, Relay states that deposits “qualify for up to $3,000,000 in FDIC insurance coverage when Thread Bank places them at program banks in its deposit sweep program,” with each program bank covering up to “$250,000, inclusive of any other deposits you may already hold at the bank in the same ownership capacity.” The coverage comes from the sweep arrangement, not from Relay, and that last clause is worth re-reading if you already bank elsewhere in the US.
If you are on the list
There is a documented exceptions route, and it is worth using properly. Relay:
“Exceptions can apply based on Thread Bank’s case-by-case review. If you think your situation may qualify for an exception, contact our Customer Experience team before submitting an application so your case can be flagged for review.”
The operative word is before. A rejected application leaves a record; a flagged enquiry does not. If you have something genuinely unusual — a second passport from an unrestricted country, long-standing residency elsewhere, a minority stake below the beneficial-owner threshold — that is the conversation to have, and to have first.
We will say the obvious thing plainly, because people ask: Bizstartz cannot get a Relay account for anyone on that list, and neither can anyone else. No formation agent, introduction, nominee arrangement or US address service overrides a sanctions-adjacent policy held by a chartered bank. Anyone promising otherwise is either selling you a rejection or selling you fraud.
What to try instead
If Relay is closed to you, the useful question is which restriction caught you.
- Caught by citizenship, but you live somewhere unrestricted? Check Mercury’s list first. Mercury tests residence, so this is precisely the case where Mercury may say yes to someone Relay refused.
- On both lists? Then neither of these two is open to you. Wise Business is where most guides point next, but Wise’s own rules are narrower than those guides suggest: Wise does not issue USD account details to accounts with an address in Nigeria or Pakistan, among other countries, and it does not accept a registered agent or virtual address as a business trading address (both checked 7 October 2026). Wise is also a money services business, not a bank. Read the Wise section of our Mercury prohibited countries guide before you rely on it.
- Not sure which applies? Our breakdown of US banking and payment access by country is organised by where you are rather than by provider.
Common questions
Does forming a Wyoming or Delaware LLC get round Relay’s country rule?
No. Relay’s own sentence is “regardless of where the business itself is registered.” The entity’s state has no bearing on it. Forming a US LLC is still necessary — it is just not sufficient.
My co-founder holds a listed passport but only owns 10%. Does that block us?
Relay applies the rule to owners “named on the Relay Account application, including beneficial owners,” and defines beneficial ownership at 25% or more, or significant management responsibility. Someone at 10% with no management role would not normally be named. Someone at 10% who runs the company might be. This is exactly the fact pattern to put to Relay’s Customer Experience team before you apply rather than guessing.
I hold two passports, one listed and one not. Which one counts?
Relay does not publish an answer to this, and we are not going to guess at one. Declare both — concealing a citizenship is the fraud problem described above — and ask for the case to be flagged for review in advance.
Relay opened my account. Why can’t I send an international wire?
Almost certainly the beneficial-owner citizenship list on Relay’s international wires page, which is a separate and much longer list than the account-opening one. Nepal, the Philippines, Vietnam, Sri Lanka and Nigeria were all on it as of 4 November 2026.
Is Relay free?
We have not checked Relay’s current pricing, account limits or wire fees, so we are not going to quote any. Take those from Relay’s own pricing page.
Checked, and when to check again
Every Relay fact on this page was read directly from Relay’s help centre on 4 November 2026. All four country lists carried “Updated August 11, 2026” on that date. Nothing here comes from a review site, an affiliate roundup or another formation agent’s blog.
Relay’s own caveat is the right note to end on: the list “reflects current Thread Bank policy and applicable U.S. sanctions, and it can change without notice.” Sanctions move, banking partners change their risk appetite, and a country can be added between your research and your application. Open Relay’s prohibited-countries page and read it yourself on the day you apply. It takes a minute and it is the only version that is authoritative.
If you would rather someone check all four lists against your specific citizenship, residency and ownership structure before you start filling in forms, that country screening is part of our US bank account setup service at $100, which also covers application preparation. We will tell you if the honest answer is that no provider will take you — that is a more useful outcome than a rejection on file.
Ready to start? Book a free consultation and we will map out your US LLC formation, EIN, banking and the right state for your country.

Ready to start your company?
Bizstartz handles formation, EIN, banking and compliance for founders worldwide.